Articles

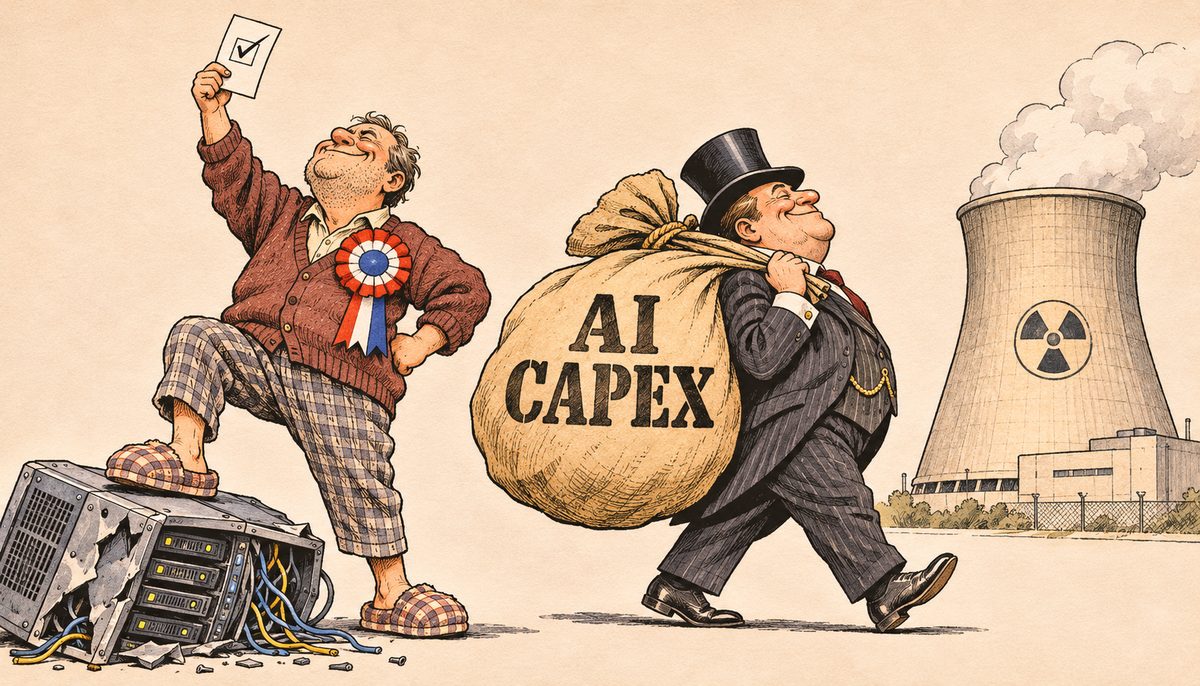
Democracy beat capital – this time: The AI boom bends rather than breaks: the Three-Phase AI Economy after the midterms

Voters across America have just told the AI boom what they think of data centres and their electricity bills, and Insightview has redrawn its Three-Phase AI Economy as a result. Democracy beat capital this time. But what happens when the grievance is no longer the power bill?

Read more β†’
AI-generated

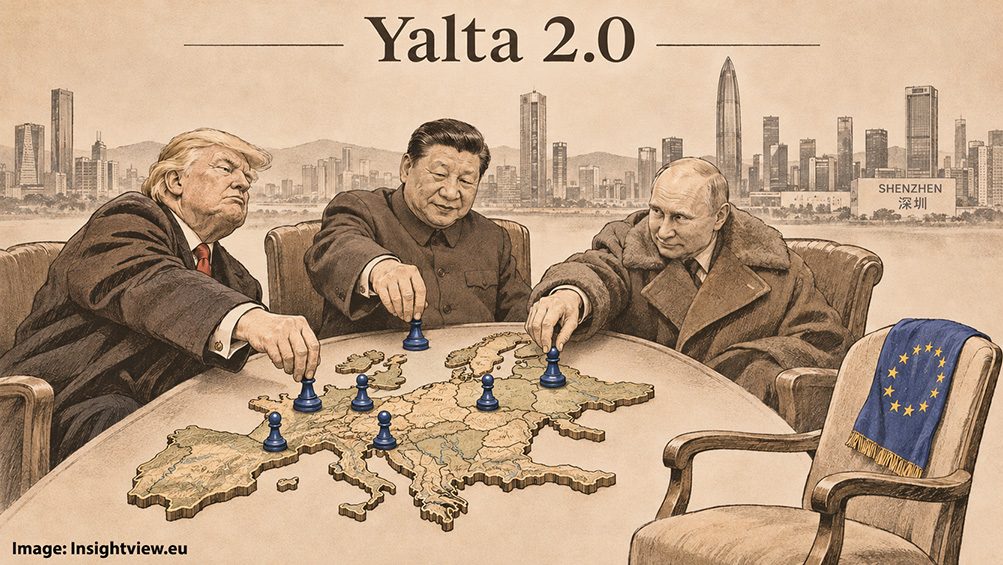
Yalta 2.0: Russia may be the weakest power in Shenzhen, but Europe is the most vulnerable

Many Europeans have feared this meeting since February 2022: the leaders of the US, China and Russia gathering in Shenzhen to settle Europe's future without Europe at the table. Unlike at Yalta, however, all three arrive wounded. So which party is really the weakest, and what will Europe's empty chair end up costing?
The bond market has bought the right destination, but not the price of the journey

America has just posted its largest October deficit on record, the Fed is raising rates again, and the AI boom is turning into an energy bill. Yet the bond market's long-term inflation expectations have hardly moved in two years. Investors seem to know where the economy is heading. Have they priced how long, and how expensive, the road there will be?

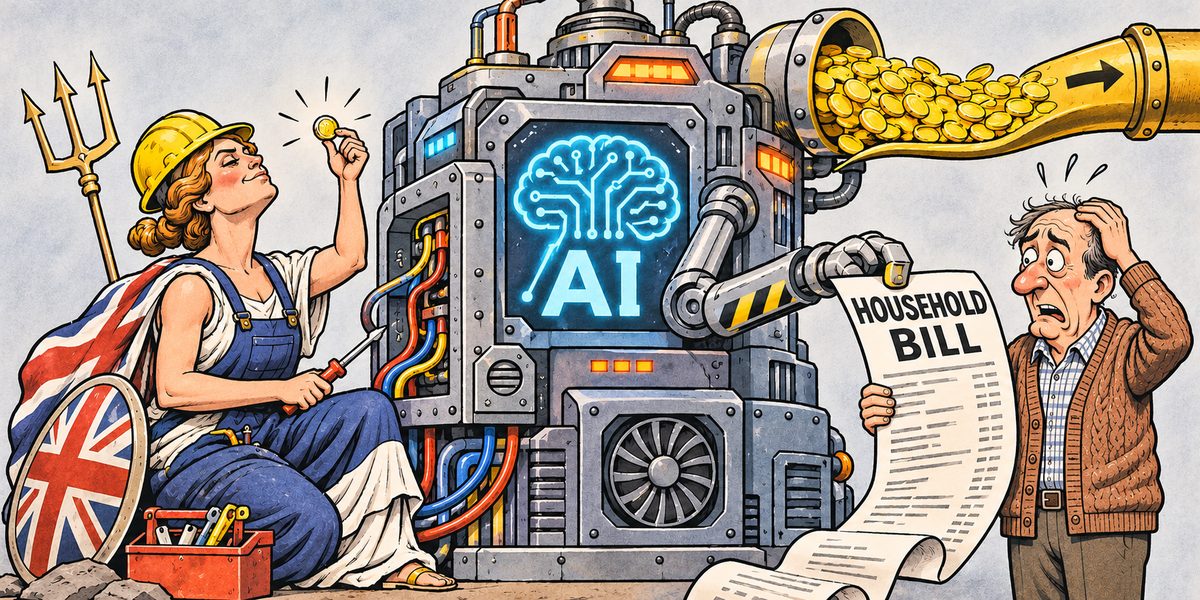
Britain sells the AI installation while its households receive the bill. The AI boom shows up in output, not in household wealth

On the same Thursday morning, Britain reported its fastest growth since early 2024, powered by programmers wiring AI into banks and insurers, while surveyors warned that house prices are falling. Britain is clearly being paid to install AI. But when the technology finally delivers, who will actually be collecting the money?

Weekly Update - November 11, 2026

Three delegations sat at the table in Abu Dhabi. Europe waited outside the room in which its own security order was being discussed, in words Moscow has used since 2008. Meanwhile Sweden keeps growing, euro area inflation hits 4% and Washington shields the chief executive of Nvidia. Who is actually negotiating on Europe's behalf, and who will pay the bill?

AI is changing, but inflation pressure is not. The AI boom has moved from chips to power, and inflation has moved with it

Since the midterms, data centres have been put under a political lid and petrol is getting cheaper. Investors could be forgiven for thinking the Fed's inflation problem is fading with them. Yet on Tuesday a Fed governor said he would hike even on good news, and hours later the price data came in. So what is still feeding the fire?

Who pays for progress? AI's free lunch is over, and the barriers are back. Nvidia and Donald Trump

For three years, a picture of a cat in a spacesuit riding a flamingo cost nothing, at least for whoever asked for it. Last week, someone else sent the bill back, from a closed-door summons in Washington to a Texas governor-elect and activists inside a Microsoft site in Amsterdam. Markets call it a correction. What exactly would it be correcting back to?

"Correction" may not survive unruly Democrats – nor may the Democrats' own victory

On Wednesday, investors bet that a Democratic Congress would save the AI spenders from themselves. On Thursday, they changed their minds. The S&P 500 is still only in correction territory, but chip stocks tell another story. Is "correction" still the right word when nobody knows what unruly Democrats will do – or what it may cost them?

The midterms repriced the war, not capital: Why Europe's bill still stands

Democrats took both chambers on Tuesday and oil collapsed, so bond investors should have been celebrating. Beneath a calm 10-year yield, however, two opposite moves cancelled out, and one of them matters far more for Europe than the election itself. What exactly did American voters change, and what did they leave on Europe's bill?

Weekly Update - November 4, 2026

For two years, markets have priced the will of one man. From January, they must also price a Congress with the power to refuse him. Republicans lost big, the president kept his veto, and the bond market barely blinked. So who actually holds the power now, and why does Tuesday's vote leave Europe's bill where it was?

More β†’